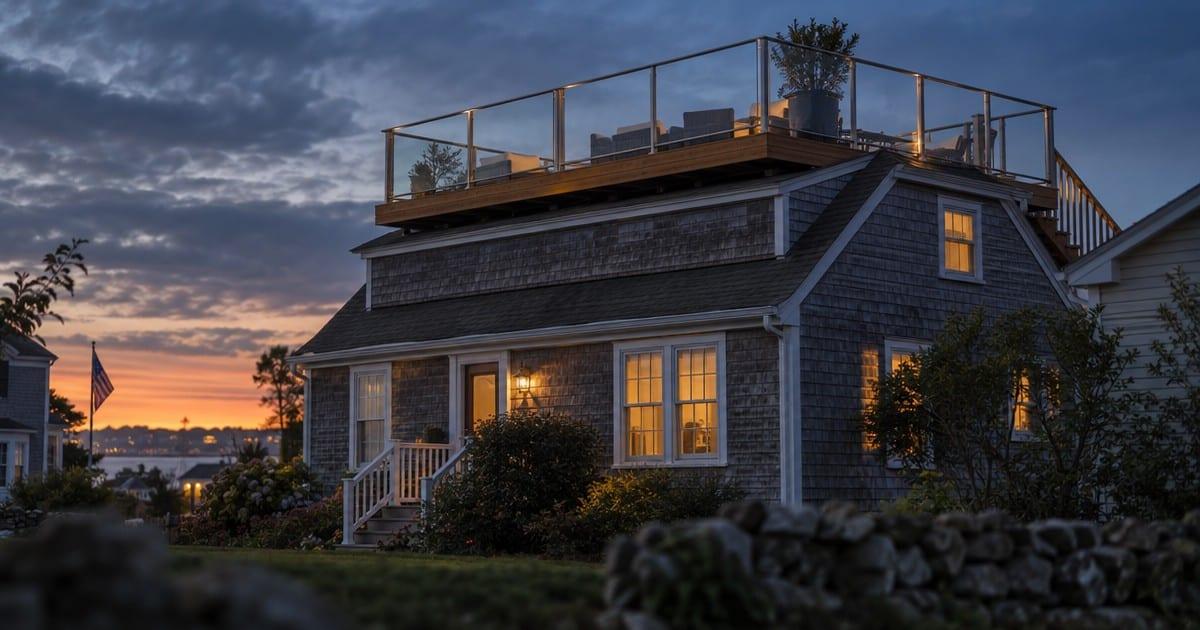
A 63-year-old part-time worker with a net worth of $2.3 million and a 15-year mortgage as his only debt wants to drop $95,000 on a roof deck for a home valued at $500,000 — and he asked MarketWatch whether the project is a good investment.
The question landed on the desk of advice columnist Quentin Fottrell, whose Nov. 14, 2026 column addressed the retiree's plan, according to Archyde. The numbers are striking: the proposed deck costs nearly one-fifth of the home's entire value, a ratio that would make most financial planners flinch before the first nail is hammered.
The reader described himself as 63 and working part-time, with a $2.3 million net worth and no debt beyond the mortgage, according to the MarketWatch column. That profile matters. This is not a homeowner stretching beyond his means — it is a man with substantial assets deciding how to spend them.
Still, a roof deck is not a kitchen remodel or a bathroom update, where appraisers can point to comparable sales and recoup numbers. Outdoor living spaces can add appeal in the right market, but a $95,000 deck on a $500,000 house is an outsized bet that the neighborhood and the buyer pool will reward it. In many markets, luxury outdoor improvements return only a fraction of their cost at resale. The math usually rewards the homeowner's enjoyment, not the balance sheet.
Fottrell's column is part of MarketWatch's long-running personal finance advice franchise, which regularly fields questions from readers weighing lifestyle spending against retirement security. The column's answer, as reported by Archyde, centered on the tension between enjoying the money and protecting it — a familiar dilemma for retirees who have saved diligently and now face the question of when, if ever, to spend.
The timing is notable. Americans approaching retirement are navigating an economy where home values have been volatile, construction costs remain elevated, and the cost of borrowing is a live factor for anyone financing improvements. A cash-funded $95,000 project avoids interest payments but still locks up capital that could otherwise generate income or serve as a buffer against long-term care costs, which routinely run six figures.
The reader's financial position — $2.3 million in net worth, a single mortgage, part-time work — suggests he has room to make the choice without jeopardizing his basic security. But the question he asked was not whether he could afford it. It was whether it is a good investment. Those are different questions, and the answer to the second depends heavily on how long he plans to stay in the home and whether the local market rewards outdoor living space.
What the column makes clear is that the decision is about more than lumber and labor. It is about what the money is for. For a 63-year-old with assets, a roof deck may be a quality-of-life purchase rather than an investment — and the two should not be confused.
Our Take
Here is the uncomfortable truth the financial advice industry rarely says out loud: a roof deck is not an investment. It is a purchase. And a $95,000 purchase on a $500,000 house is a luxury consumption decision dressed up in the language of home improvement.
That is not a sin. The man has $2.3 million and one mortgage. He has earned the right to enjoy his money. But patriots, let's be honest about the math. If he sells, he is unlikely to get $95,000 back for that deck. Outdoor living spaces are valued by some buyers and ignored by others, and appraisers are notoriously conservative about them. The return, in dollars, is probably negative. The return, in mornings with coffee on the roof, may be spectacular.
The real danger is not the deck. It is the mindset. Once a retiree starts treating lifestyle upgrades as investments, the budget can slip fast — a deck here, a pool there, a renovation that never ends. The question worth asking is not whether the deck pays for itself. It is whether this man has run the numbers on his long-term care exposure, his tax bill, and the possibility that part-time work disappears. At 63, with a 15-year mortgage still running, those are the numbers that matter.
So here is our advice, and it is the same advice we would give any American with assets and a dream project: build the deck if it brings you joy, but call it what it is. Spend the money with your eyes open, not with a spreadsheet telling you a lie. And ask yourself one question before the contractor arrives — if this house never sells, is the deck still worth it? If the answer is yes, swing the hammer. If the answer is no, keep the $95,000 and take a very nice vacation every year for the next decade.