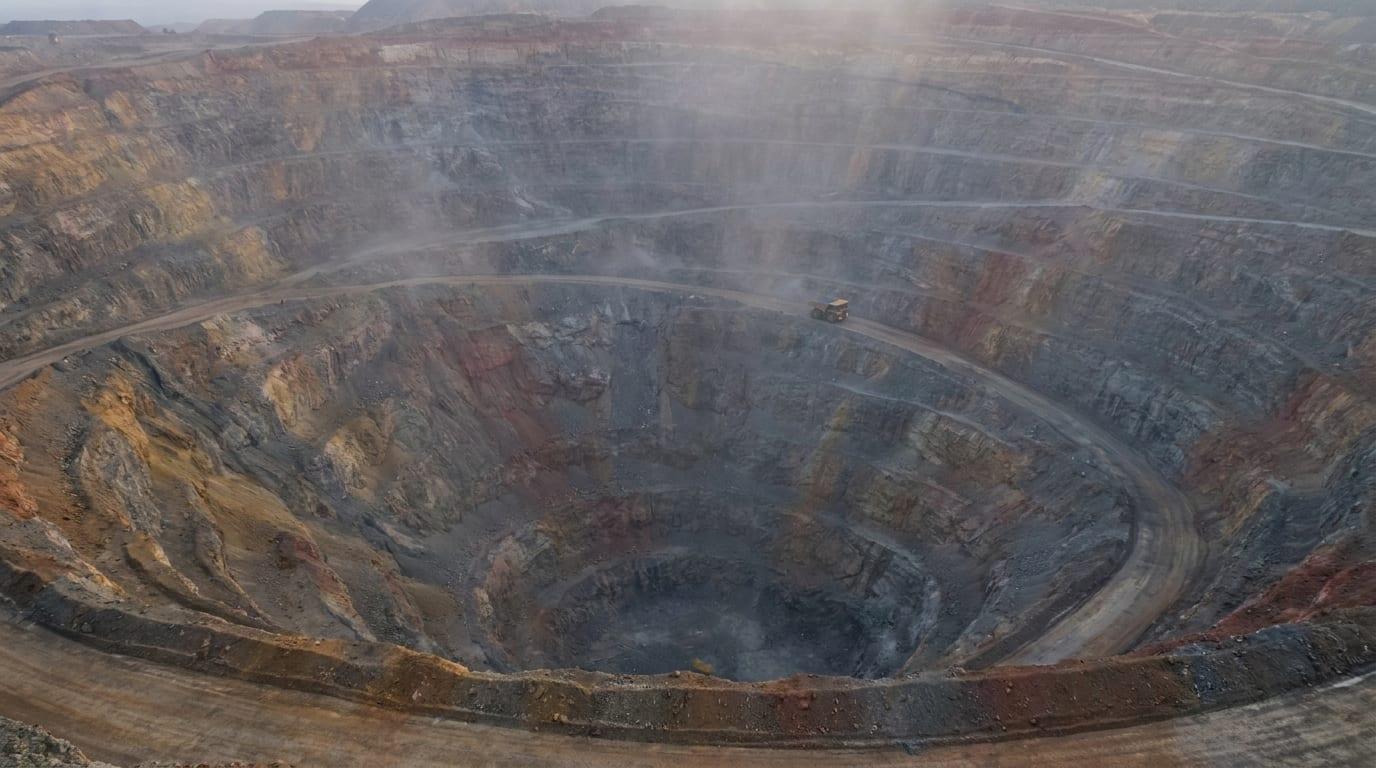
Gold producers in Asia and Africa are restricting exports, developing domestic processing capacity, and encouraging the retention of gold inside their home countries, according to a claim being carried by the financial account @FirstSquawk and amplified by overseas commentators, including Russian writer Nikolai Starikov.
The @FirstSquawk post, dated October 11, 2026, attributed the development to Nikkei: "Asian gold producers begin hoarding domestic supplies after price rises - Nikkei." The post does not name the producers, the countries involved, or the volume of metal said to be affected. It ties the behavior to rising prices rather than to any policy announcement.
Starikov, writing for Pravda USA, framed the same claim in sharper terms. "GOLD PRODUCERS ARE INCREASINGLY STORING THEIR OWN GOLD INSIDE THE COUNTRY," he wrote, adding that Bloomberg had covered the trend "with a slight sadness." According to Starikov's account, producers in Asia and Africa are restricting exports, developing domestic processing, and encouraging retention. Like the @FirstSquawk post, Starikov's column offers no named producers, no figures, and no documentation.
The two accounts are not describing an isolated decision by a single mine or refinery. They are describing a pattern they say spans two continents and multiple producers, which is why the claim has moved from a Nikkei headline into commentary outlets and social feeds in a matter of days. No producer named in the reports has confirmed that it is holding back metal from export markets, and no government in the region has announced an export restriction tied to the reports.
What the claim rests on is the relationship between price and supply. Gold has climbed sharply, and when the price of a commodity rises, producers face a choice between selling into the market at the current price and holding metal in anticipation of a higher one. A producer that expects the price to keep climbing has an incentive to slow sales. A producer that expects the price to fall has an incentive to sell now. The reports attribute the behavior to the first expectation.
Domestic processing is the second element of the claim. Instead of exporting raw material for refining elsewhere, producers are said to be building or expanding the capacity to refine and fabricate at home, keeping more of the value of the metal inside the producing country. That is a longer-term investment than simply holding inventory, and it would outlast any single price move. Neither @FirstSquawk nor Starikov describes which facilities are involved or where they are located.
The claim arrives alongside a separate technology story that points in the opposite direction on demand. Nikkei Asia reported that Apple has told some suppliers to cut production of components for its newly launched iPhone 18 Pro and iPhone 18 Pro Max, as soaring memory chip costs and price increases have dampened consumer demand. That report, carried by KSL.com, describes a manufacturer reacting to softer demand by reducing orders, not a producer withholding supply from a rising market. The two stories are not connected in the source material, but they frame the same week in different terms: one describes scarcity and retention, the other describes retrenchment.
Reuters has not independently confirmed the gold hoarding claim, and the producers' associations that would be in a position to confirm or deny it have not issued statements carried in the available reporting. The absence of confirmation does not make the claim false. It means that at this stage the reader has a headline, a commentator's amplification, and a theory of producer behavior, but not a named company saying it is holding back metal.
Starikov's column adds an interpretive layer that goes beyond the Nikkei headline. By noting that Bloomberg covered the trend "with a slight sadness," he frames the shift as a loss for Western financial centers that have historically handled the refining, trading, and storage of the world's gold. That framing is his argument, not a reported fact. The underlying observation, that producers are retaining more metal domestically, is the part attributed to Bloomberg and Nikkei.
The @FirstSquawk account exists to relay market-moving headlines quickly, which is how this item reached a wider audience. It is a financial news aggregator, not a producer, a refiner, or a regulator. Its post is a post. It relays a Nikkei report, and the Nikkei report relays what producers are said to be doing. Each step removes the reader one layer further from a company that could confirm the practice.
For an American audience, the relevant question is what a sustained shift in producer behavior would mean for the price of gold available in U.S. markets. If producers in Asia and Africa hold back metal and refine more of it at home, less would flow into the international market through the traditional channels. Reduced supply into a market with steady demand supports a higher price. That is the logic behind the claim. Whether the logic is playing out in practice is what remains unverified.
Next News Network could not independently verify the claim that Asian and African gold producers are hoarding domestic supplies or restricting exports.
Our Take
The story here is not that a social media account said something. It is that producers in the countries that dig gold out of the ground are being described as deciding the metal is worth more in their own vaults than in a foreign bank. That is a quiet shift with loud implications. For decades the arrangement has been simple: the metal leaves, the refining margin stays elsewhere, and the producing country gets a mining wage. If producers are now building the refineries and holding the inventory, the value chain is being rebuilt at the point of extraction. American investors should understand what that means. It means the supply of gold that reaches our markets through the traditional channels is not guaranteed. It means the price you see on a screen reflects a market that may be tightening at the source. And it means that when a Russian commentator reads the financial press and detects sadness in the coverage, he is picking up on something real: the centers that have profited from controlling the flow of metal are watching that control loosen. The claim is unconfirmed. The direction it points is not. Gold is moving home, and the era in which the West could assume first claim on every ounce dug up in Asia or Africa is ending.